In this article
- Which freelancers need a 2026 form?
- What 1099 paperwork for freelancers needs before you start
- Step 1: Confirm this person is really a freelancer
- Step 2: Get a W-9 before the first payment
- Step 3: Put the work and the price in writing
- Step 4: Pay in a way that leaves a trail, and log it
- Step 5: In January, total each freelancer and apply the threshold
- Step 6: File Form 1099-NEC and send the freelancer's copy
- Step 7: Check your state
- The records to retain after filing
- Carry the payment route into the year-end ledger
1099 Paperwork for Freelancers: From the First Invoice to Filing
Official sources checked: October 28, 2026
What should you collect before paying a freelancer’s first invoice, so you are not chasing their tax details at year-end? You hired a freelance designer to redo your menu and website banner, and the first invoice just landed in your inbox. Most 1099 paperwork for freelancers happens long before tax season, and the order matters because each step produces something the next one needs. Skip the first form, and January becomes a chase for a taxpayer ID from someone you haven't talked to in months.
At this hypothetical bakery in 2026, the owner pays a freelance graphic designer $2,400 across three invoices and a freelance photographer $1,500 for a single shoot. Assume both are U.S. sole proprietors, all payments are for business services, and neither had backup withholding. Those facts let us isolate the annual reporting threshold without treating every payment situation as identical.
Which freelancers need a 2026 form?
Collect Form W-9 before you pay anyone, pay in a way you can trace, and log every payment under the freelancer's name. In January, total what you paid each person. For payments made in 2026, you generally file Form 1099-NEC(nonemployee compensation report) for anyone you paid $2,000 or more for services, up from $600 for 2025 payments. Both the IRS copy and the freelancer's copy are due January 31, and because January 31, 2027 is a Sunday, the practical deadline for 2026 forms is Monday, February 1, 2027.
What 1099 paperwork for freelancers needs before you start
You need three things in place before the first payment goes out. The first is a signed W-9 from the freelancer, which gives you their legal name, taxpayer ID, address, and federal tax classification. The second is a payment log, which can be a spreadsheet as long as every row ties a payment to a person and an invoice. Last, pick a filing route for January, either your accounting or payroll software or the IRS's free IRIS portal.
Step 1: Confirm this person is really a freelancer
Everything after this step assumes you're paying an independent contractor, so check that first. The IRS looks at how much control you have over how, when, and where the work gets done, and some states apply a stricter test. New Jersey and California, for example, use versions of an "ABC test" that presume a worker is an employee unless you can show otherwise. Both states' official guides are linked in the sources below.
The bakery's designer sets her own hours, uses her own software, works for other clients, and delivers finished files. The photographer works the same way. If your answers look more like "I tell them when to show up and how to do it," stop here and read our first-hire guide before going further.
Step 2: Get a W-9 before the first payment
The W-9 is the input for everything that happens in January, which is why it comes before money changes hands. It's meant for U.S. persons; a foreign individual may need Form W-8BEN, while other foreign payees can need different W-8 forms. Work performed abroad and work performed in the United States can have different sourcing and withholding rules. Stop this domestic W-9 workflow and ask a CPA which documentation applies before paying a foreign person.
If a freelancer doesn't give you a taxpayer ID, IRS rules can require you to hold back 24% of reportable payments as backup withholding and send it to the IRS yourself. Asking up front is a lot easier than explaining a 24% cut on someone's second invoice.
The tax classification box matters too. Payments to corporations generally don't need a 1099-NEC, with exceptions such as attorneys, so the W-9 tells you early whether this person will need a form at all. Store W-9s somewhere secure, since many freelancers write their Social Security number on them. You're done with this step when the form is signed, the name matches the invoices, and the ID field isn't blank.
Step 3: Put the work and the price in writing
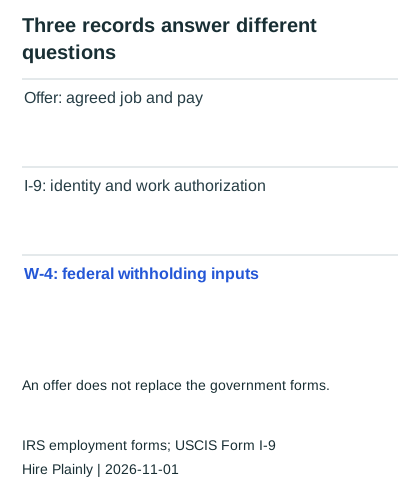
A short agreement or statement of work isn't a tax form, but it gives your payment log something to point to. It should name the deliverables, the price or rate, and how invoices get paid. When a number on the 1099 is questioned later, the agreement and the invoices are how you show where it came from.
Step 4: Pay in a way that leaves a trail, and log it
How you pay changes what you report, and this is where many owners slip. Payments by check, cash, or bank transfer count toward the 1099-NEC total. Payments made by credit card, debit card, or through certain third-party payment networks don't belong on your 1099-NEC, because the card processor or network reports them on Form 1099-K instead.
Here's the bakery's log at the end of 2026. Read the "Counts toward 1099-NEC" column first, because that's the one January depends on.
| Date | Freelancer | Invoice | Amount | Paid by | Counts toward 1099-NEC |
|---|---|---|---|---|---|
| Mar. 4 | Designer | #101 | $800 | Bank transfer | Yes |
| Jun. 10 | Designer | #114 | $800 | Bank transfer | Yes |
| Sep. 2 | Designer | #126 | $800 | Bank transfer | Yes |
| Jul. 18 | Photographer | #7 | $1,500 | Check | Yes |
Hypothetical numbers for illustration only.
Now change one thing. If the bakery had paid the designer's September invoice with a business credit card, her reportable total would drop from $2,400 to $1,600. That's under the threshold, so no 1099-NEC would be required, even though she was paid the same amount. Reconcile each invoice to the bank or card statement, then compare the payment-method totals with the amount you plan to report. A payment app is not automatically a qualifying third-party network transaction; verify how the specific business payment was processed.
Step 5: In January, total each freelancer and apply the threshold
Add up each person's "Yes" rows. The designer comes to $2,400, which clears the $2,000 threshold, so she gets a 1099-NEC. The photographer comes to $1,500, which doesn't, so the bakery has no federal 1099-NEC to file for him.
Two things don't change with the threshold. The photographer still owes tax on his $1,500, because the threshold decides who gets a form, not what counts as income. And the bakery should still keep his W-9 and invoices, because next year's work could push him over the line. The $2,000 figure is scheduled to adjust for inflation after 2026, so check the current number each January. If you made backup withholding, file the required 1099-NEC regardless of whether the annual payment reached the threshold.
Step 6: File Form 1099-NEC and send the freelancer's copy
Set up the filing route before January. The IRS IRIS page requires a Transmitter Control Code (TCC) for its free Taxpayer Portal. Apply ahead of filing season and confirm that access works; choosing IRIS on the deadline does not make you ready to submit.
Prepare a year-end worksheet with one row per payee: W-9 legal name, tax classification, mailing address, reportable total and state filing decision. Keep the full taxpayer ID in the restricted tax file rather than in the general operating spreadsheet. Compare the designer's worksheet amount with all three invoices and the bank statements before entering the form.
The designer's 2026 form shows $2,400 in box 1a, nonemployee compensation, under the current IRS instructions. You send her copy and file the IRS copy by the same deadline, which for 2026 payments is February 1, 2027. If you file 10 or more information returns of any type in a year, the IRS requires you to file them electronically, and IRIS lets you do that at no cost.
After submission, save the acknowledgement and check whether the return was accepted or rejected. Correct rejected records and confirm acceptance; a saved draft or uploaded CSV is not the same as an accepted return. Separately record when and how you furnished the recipient copy, because IRS submission does not deliver it for you.
If you file on paper instead, you need the official scannable red-ink Copy A plus Form 1096. A Copy A printed from the IRS website isn't accepted. Most owners with one or two freelancers find e-filing simpler for that reason alone.
If something's wrong after you file: a wrong amount is fixed with one corrected 1099-NEC. A wrong taxpayer ID or name on a paper filing takes two steps: a corrected form that zeroes out the original, then a new form with the right information. IRS Publication 1099 walks through both.
Step 7: Check your state
Federal filing isn't the whole job, because states set their own rules. New Jersey's employer guide calls for a state filing when you paid $1,000 or more or withheld New Jersey income tax, a lower bar than the new federal one. New York doesn't require a separate annual 1099 return from most payers, and Texas has no state income tax return for these forms.
California has two separate steps. Its tax agency uses the same $2,000 threshold for 2026 nonemployee pay and accepts many forms through the IRS Combined Federal/State Filing program. Separately, California's EDD wants a Form DE 542 for any individual contractor, sole proprietor or single-member LLC(state-law business entity) you're required to report on Form 1099-NEC. It's due 20 days after you either pay that person $600 or more in the year or sign a contract worth $600 or more, whichever happens first.
If the bakery were in California and signed a $2,400 agreement with the designer in February, the DE 542 would be due 20 days after signing, before her first invoice was even paid. The photographer's $1,500 stays under the federal service-payment threshold in this example. Before deciding that no DE 542 is due, check all EDD conditions, including whether another federal information-return requirement applies. Do not apply the $600 trigger without checking the separate federal-reporting condition.
The records to retain after filing
Once the forms are filed and the copies are sent, your federal filing for the year is done. Whatever state steps apply to you, from the list above, are what's left. What carries over is the W-9 file, the payment log, and the habit of asking for a W-9 before the first payment. If a freelancer's role grows into regular hours under your direction, go back to Step 1, because that change can turn the paperwork question into an employment question.
Carry the payment route into the year-end ledger
Add a payment-method column when the invoice is paid. In the example above, three invoices can belong to one contractor while the card-paid invoice follows a different reporting route. The year-end reviewer needs the invoice, payment reference and exclusion reason, not just a total copied from the expense account.
Keep a W-9 receipt flag in the operating tracker and store the actual form securely. When the project ends, also review system access and the outstanding invoice. Ending the engagement does not remove the later filing task, so assign the year-end check before closing the project.
This article is general information, not legal or tax advice. Rules change and every business is different, so check with your state agency, an employment attorney, or a CPA before making decisions.